
WIFO-Konjunkturtest
Part of the Joint Harmonised EU Programme
of Business and Consumer Surveys
WIFO-Konjunkturtest
Part of the Joint Harmonised EU Programme
of Business and Consumer Surveys
WIFO-Konjunkturampel (economic traffic light)
The results of the WIFO-Konjunkturtest (business cycle survey) for September show a slight improvement in economic assessments. The WIFO-Konjunkturklimaindex stood at –1.4 points (seasonally adjusted), 0.2 points higher than in August. Assessments of the current situation deteriorated slightly (–1.3 points) and, at –1.5 points, remained in sceptical territory. Economic expectations improved (+1.7 points) but, at –1.3 points, also remained below the zero line. Across all sectors, there were slight declines in assessments of the current situation. As regards expectations, there was a slight decline in the retail sector, a sideways trend in services, a slight improvement in the construction sector and a more marked improvement in the manufacturing sector.
Economic Sentiment and Employment Expectations Decline in Both the EU and the Euro Area
In September 2026, the Economic Sentiment Indicator (ESI) declined mildly in both the EU (–0.4 points to 97.9 points) and the euro area (–0.5 points to 97.9 points) compared to August. The Employment Expectations Indicator (EEI) receded slightly more markedly (EU: –0.6 points to 98.3 points; euro area: –1.3 points to 97.5 points). After trending upwards since May, both indicators again drifted away from their long-term average of 100 points.
Credit Conditions of Austrian Companies
The credit questions of the WIFO-Konjunkturtest (business cycle survey) allow us to present the assessments and experiences of companies with regard to bank lending. The credit questions are asked quarterly in February, May, August and November.
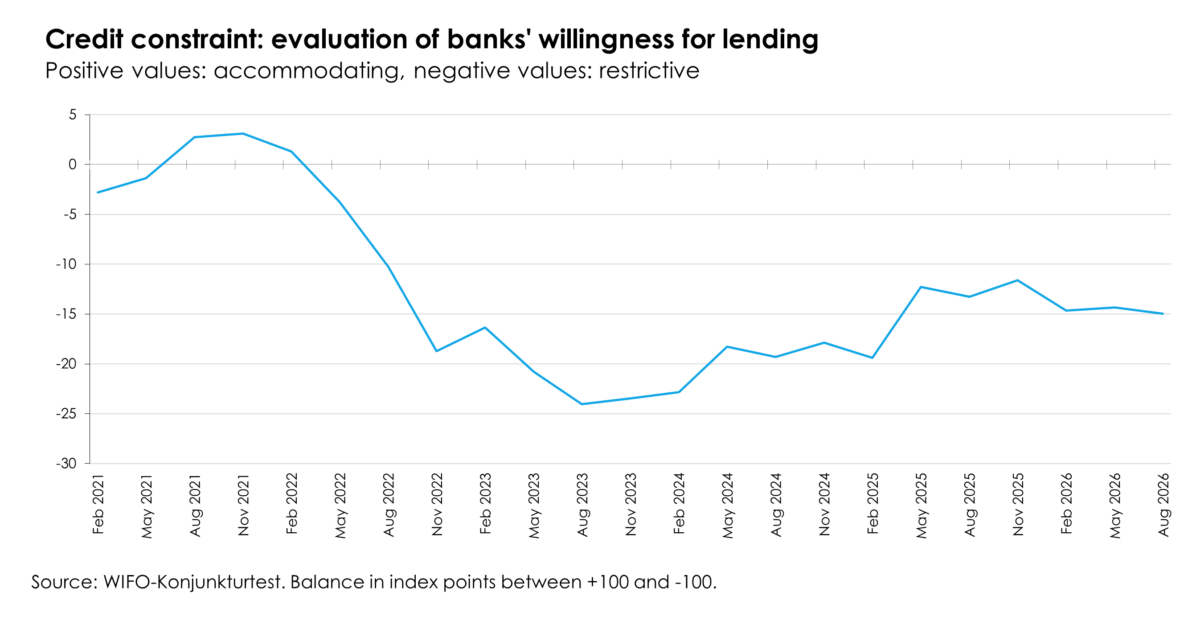
In August 2026, companies' assessments of banks' willingness to lend – defined as the balance between the proportion of businesses describing banks' lending practices as accommodating (positive values), and the proportion of firms describing banks' lending as restrictive (negative values) – deteriorated slightly compared with the previous quarter (–0.7 points) and stood at –15.0 points, in negative territory. Differences are evident across company sizes: the barrier to obtaining credit is higher for smaller companies (fewer than 50 employees) (–17.8 points) than for medium-sized companies (50 to 250 employees: –9.9 points) and large companies (more than 250 employees: –7.8 points).
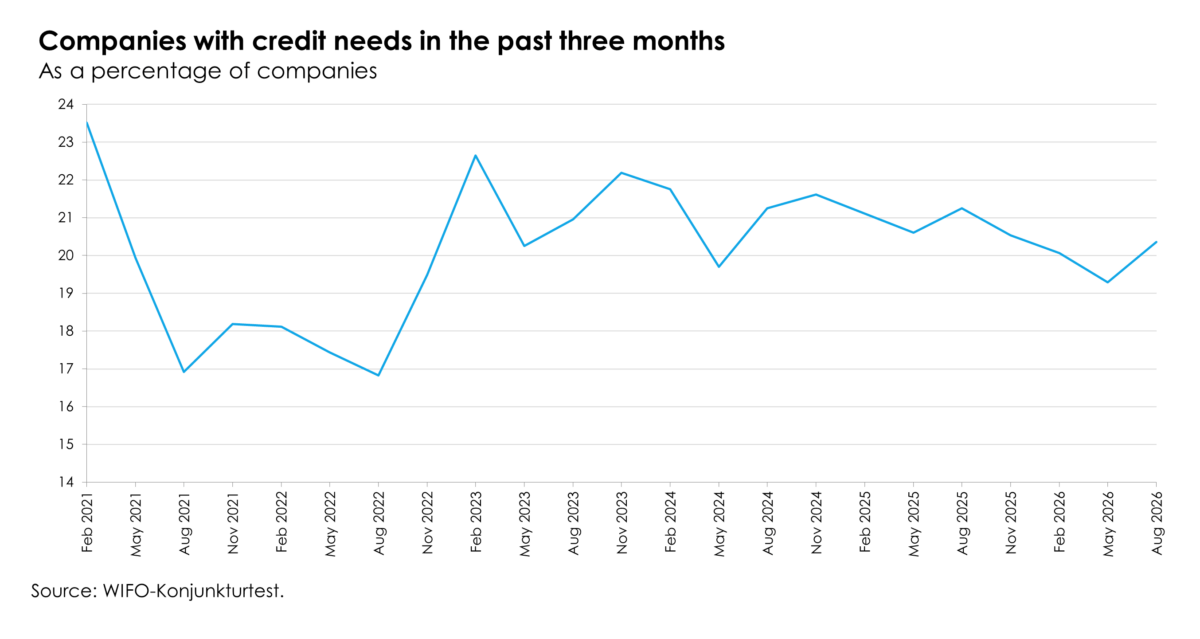
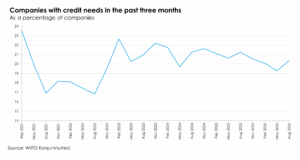
The survey results show an overall increase in demand for credit (excluding the retail sector), with a figure of 20.4 percent (long-term average: 20.5 percent), representing a rise of 1.1 percentage points compared with the previous quarter. In the manufacturing sector, demand for credit remained above average (22.1 percent of firms reported a need for credit); in the retail sector (17.6 percent), it rose significantly, whilst demand for credit in the service sectors (19.4 percent of firms) and in the construction industry (20.0 percent) remained at average levels despite increases. By company size (excluding the retail sector), 17.6 percent of smaller companies (fewer than 50 employees) recently reported a need for credit, as did 26.0 percent of medium-sized companies (50 to 250 employees) and 22.3 percent of larger companies (more than 250 employees).
Of the companies with credit needs (excluding the retail sector), around 32.8 percent had to make concessions regarding the amount or the terms (18.8 percent reported less favourable terms, 6.3 percent a lower amount, and 7.7 percent both less favourable terms and a lower amount than expected). This figure is below the average for the past five years (34.4 percent). Around 38.1 percent of businesses requiring credit were able to secure it as expected (5-year average: 36.9 percent). At 29.7 percent, the proportion of businesses requiring credit that did not receive a loan or had not applied for one was slightly above average (5-year average: 28.8 percent; around 6.0 percent of all companies surveyed) because their loan application was rejected by the bank (5.8 percent), the terms were unacceptable (10.8 percent) or they had not attempted to secure a loan as they considered it futile (13.1 percent).
Credit Constraints and Credit Needs
Recent issues: WIFO-Konjunkturtest
Quarterly results of the WIFO-Konjunkturtests
Special issues: WIFO-Konjunkturtest
Recent issues: WIFO-Investitionsbefragung
Contact
(Senior) Economists

For general enquiries, please contact konjunkturtest@wifo.ac.at.